
A property inspection waiver, now called value acceptance by Fannie Mae, lets certain conventional loans skip a full on-site appraisal. It can save you hundreds of dollars and shave days off closing. It does not replace a home inspection, and you're free to turn it down if you'd rather have an appraiser's independent opinion on the property.
TL;DR:
- Value acceptance is more likely if your loan has an Approve/Eligible recommendation, a recent appraisal in CU, and a low loan-to-value ratio on a primary residence.
- It generally saves $400 to $600 in appraisal fees and cuts 5 to 10 days from your closing timeline, but skipping an independent appraisal removes a layer of market validation.
- It is unavailable for FHA, VA, USDA, jumbo, multi-unit, and some high-LTV loans, especially when mortgage insurance mandates an appraisal or recent appraisals exist within 120 days.
- You should review DU findings, ask for valuation disclosures, and consider a home inspection before declining a value acceptance offer to ensure accurate property valuation.
- Consulting with a licensed mortgage broker can provide an objective comparison between accepting the waiver and ordering a new appraisal, helping to optimize your final loan terms.
Table of Contents
- What Is a Property Inspection Waiver (Value Acceptance)?
- Who Qualifies, and What Gets Excluded?
- How Does It Affect Your Closing Timeline and Costs?
- Weighing the Pros and Cons of a Value Acceptance Offer
- What Should You Ask Your Lender Before Deciding?
- Why Clear Guidance on Value Acceptance Matters
- How Lofirate Helps You Compare Offers and Interpret Waivers
- Sources
- FAQ
What Is a Property Inspection Waiver (Value Acceptance)?
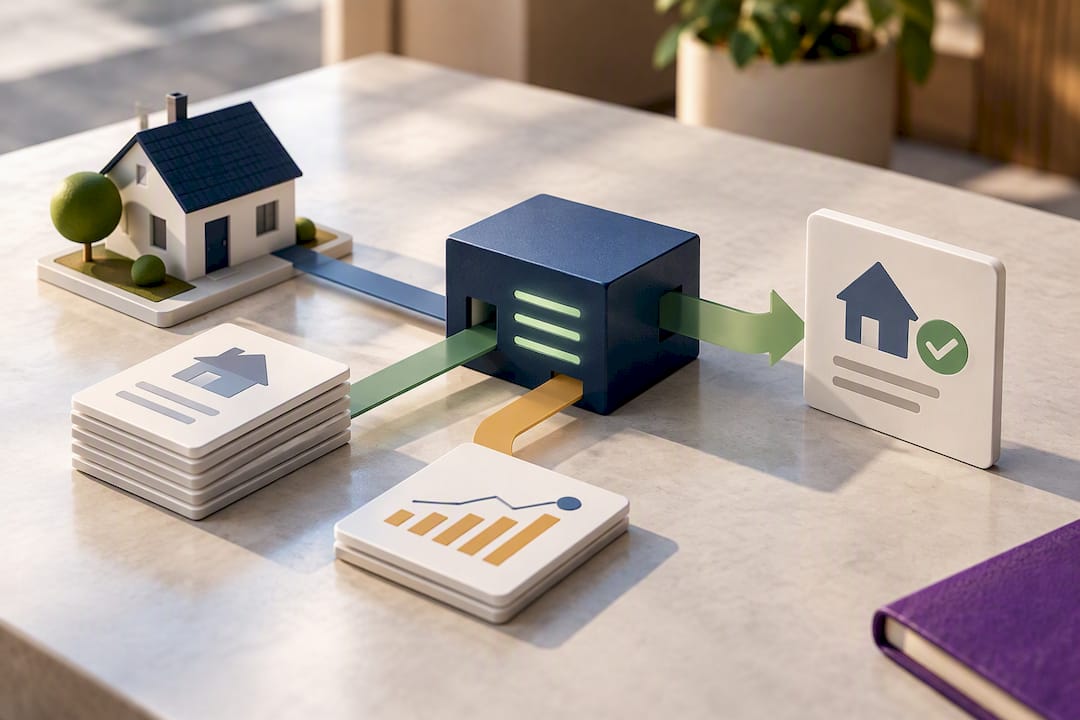
Desktop Underwriter (DU), Fannie Mae's automated underwriting system, scans your loan file and compares it against property records and prior appraisals stored in Collateral Underwriter (CU). If the data matches up well enough, DU offers to accept the lender's stated property value without sending an appraiser to the house. That's the whole mechanism. No inspector walks through, no appraiser measures square footage, no comps get pulled fresh.
Fannie Mae retired the term "appraisal waiver" on September 3, 2025, replacing it with value acceptance across its guidelines. The rebrand isn't cosmetic. It signals that the lender is accepting a value built on solid historical data, not simply skipping a step. Sometimes DU offers something in between: a property data collection, where a trained third party visits the home to document its condition without producing a full appraised value.
A few things stay constant regardless of what DU offers:
- Lenders must still provide valuation-related disclosures, since a waived appraisal doesn't waive federal disclosure rules under Regulation B.
- You cannot request a value acceptance offer directly. It's algorithmic, generated by DU on your final submission.
- If no offer appears, ordering a traditional appraisal is your only path forward.
Who Qualifies, and What Gets Excluded?
Not every borrower sees this offer, and the pattern of who does isn't random. A handful of signals tend to line up when value acceptance appears on a loan file.
- DU returns an Approve/Eligible recommendation. Manually underwritten files or anything DU flags as Ineligible never gets considered for value acceptance at all.
- A prior appraisal already sits in CU. Fannie Mae's system leans heavily on appraisal history, so a home that's been appraised recently and matches its records is a stronger candidate.
- Loan-to-value ratio stays conservative. Lower LTV loans carry less risk, which makes automated value acceptance more palatable to the investor.
- The property is a primary residence, single-family home. Owner-occupied, straightforward properties are the sweet spot.
Certain loans get excluded almost automatically. FHA, VA, and USDA loans run through different systems entirely and don't use Fannie Mae's DU value acceptance path. Jumbo and other non-conforming loans are out, as are multi-unit properties, new construction, and homes with recent major renovations that wouldn't show up in existing records. If your loan requires mortgage insurance and the MI provider mandates an appraisal, the lender cannot exercise a value acceptance offer even when DU extends one.
Two rules worth flagging on the calendar: the offer typically stays valid for a limited window, and Fannie Mae's 120-day UCDP lookback rule blocks the offer entirely if an appraisal was already uploaded to the Uniform Collateral Data Portal within the prior four months.
How Does It Affect Your Closing Timeline and Costs?
Skipping the appraisal changes the math on your closing in a couple of concrete ways. Buyers who accept typically save the appraisal fee itself, plus a few days of scheduling headaches that come with coordinating an appraiser's visit.
The typical savings: accepting value acceptance commonly saves buyers $400 to $600 in appraisal fees and cuts roughly 5 to 10 days off the closing timeline, since there's no appraiser to schedule, no report to wait on, and no revision requests to resolve.
On the lender's side, exercising a value acceptance offer isn't free of obligation. Lenders must:
- Deliver the loan with the correct special feature code, SFC 801, marking it as a value acceptance loan.
- Accept the representation and warranty implications that come with skipping an independent valuation.
- Still order a full appraisal when an MI provider requires one, when the lender has its own concerns about the property, or when regulatory requirements demand it.
- Obtain or review inspection reports for specific condition issues if the loan involved property data collection instead of a full waiver.
You're not left in the dark on any of this. Regulation B gives you the right to receive a copy of any valuation documents, including the DU findings summary, no matter which path your loan takes.
Weighing the Pros and Cons of a Value Acceptance Offer
The appeal is straightforward: less money out of pocket, fewer moving parts, and a closing date that's easier to predict because you're not at the mercy of an appraiser's schedule. For a well-documented, recently appraised home in a stable market, that trade-off usually favors accepting the offer.
The risk is just as straightforward. You lose the independent opinion an appraiser would have given you, and DU's data can carry blind spots. A finished basement, a new roof, or a kitchen remodel that never made it into county records won't factor into the automated value at all. If the seller overpriced the home relative to a soft local market, a waiver removes the one check that might have caught it.
A few factors should tilt your decision:
- Market volatility. In a fast-moving or uncertain market, a fresh appraisal is worth more than the money you'd save.
- Property uniqueness. Unusual layouts, custom builds, or rural properties with few comparable sales are harder for automated systems to price accurately.
- Recent, undocumented improvements. If you've upgraded the home in ways the public record hasn't caught up with, a waiver could undervalue what you're financing.
Pro Tip: If your home has had any major upgrade in the past two years, ask your lender whether that improvement is reflected anywhere in county or CU records. If it isn't, you may be leaving equity on the table by accepting a waiver instead of ordering a fresh appraisal.
What Should You Ask Your Lender Before Deciding?
If value acceptance shows up on your loan, treat it as a decision point, not a formality. A few concrete steps put you back in control.
- Request the DU findings summary. This document shows exactly why the automated system extended the offer and what data it relied on.
- Ask for your valuation disclosure in writing. You're entitled to it under Regulation B, and it tells you what value the lender is actually accepting.
- Check CU for any prior appraisal on file. If one exists, ask how recent it is and whether it reflects the home's current condition.
- Hire a licensed home inspector regardless of the waiver. Value acceptance says nothing about the roof, the foundation, or the HVAC system. A general home inspection covers ground an appraisal never did anyway. For older homes or unusual construction, a targeted inspection service like NoFooly Foolproof can add a second layer of condition data before you close.
- Decline it if you're not comfortable. Tell your loan officer directly that you want a traditional appraisal instead. Expect to pay the appraisal fee and add roughly a week to your timeline in exchange.
Pro Tip: Ask your loan officer this exact question: "If I decline the value acceptance offer, how many business days will the appraisal add to my closing date?" A specific number, not a vague estimate, tells you whether declining is realistic given your contract deadlines.
Why Clear Guidance on Value Acceptance Matters
Borrowers get one shot at understanding what's happening to their loan file before they sign. A waiver that saves $500 sounds like an easy win until you realize you never got an independent read on whether you're paying market value for the house.
Some platforms exist to ensure pricing and process clarity do not depend on which loan officer you happen to get. If a value acceptance offer shows up on your file and you're unsure whether to take it, comparing terms across multiple licensed brokers can give you a second and third opinion instead of hearing just one lender's word.
— LoFi
How Lofirate Helps You Compare Offers and Interpret Waivers
Deciding whether to accept a value acceptance offer often comes down to how your lender explains it, and not every loan officer explains it the same way. Some services match you with licensed wholesale mortgage brokers for a no-obligation consultation, so you can get a broker's read on your DU findings instead of relying on a single retail lender's pitch.
A wholesale broker can walk through your DU message line by line, tell you whether the value acceptance offer is competitive given your rate and terms, and flag whether an independent appraisal is worth the extra cost and days. Bring your purchase contract, your lender's DU findings summary, and your PIW or value acceptance disclosure to the consultation, and a broker can compare that offer against pricing from other lenders in Lofirate's network. If you're also weighing loan type, Lofirate's brokers cover conventional, FHA, VA, and jumbo options, so you can settle the appraisal question and the loan structure question in the same conversation. Start by requesting a free consultation through Lofirate.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- FAQs: Property Valuation | Fannie Mae
- How to Fill Out the Property Inspection Waiver (PIW) Disclosure Form - LegalClarity
FAQ
Who Qualifies for a Property Inspection Waiver?
Borrowers with a DU Approve/Eligible recommendation, a conservative loan-to-value ratio, and a primary residence with a matching prior appraisal in CU are the most likely candidates. FHA, VA, USDA, jumbo, and multi-unit loans are typically excluded, and loans requiring mortgage insurance may still need an appraisal if the MI provider requires one.
Is Waiving an Appraisal a Good Idea?
It depends on your market and your property. Accepting value acceptance usually saves $400 to $600 in fees and 5 to 10 days of closing time, but it skips the independent valuation an appraiser would provide, which matters more in volatile markets or on unusual properties.
How Common Are Appraisal Waivers?
Value acceptance offers appear most often on conventional refinances and purchases where DU already has strong data, such as a recent appraisal on file in CU. Exact frequency varies by lender and market, and the offer disappears automatically once conditions like the 120-day UCDP lookback rule or MI requirements rule it out.
What Is a Value Acceptance Offer and How Does It Work?
Value acceptance is an automated offer from Desktop Underwriter that lets a lender accept a stated property value without ordering a full appraisal, based on existing property data and appraisal history. You can't apply for it directly. It either appears on your final DU submission or it doesn't, and you can always decline it in favor of a traditional appraisal.